Serving Louisiana, Mississippi & Texas property owners Call 844.975.2100 · Book a phone consultation
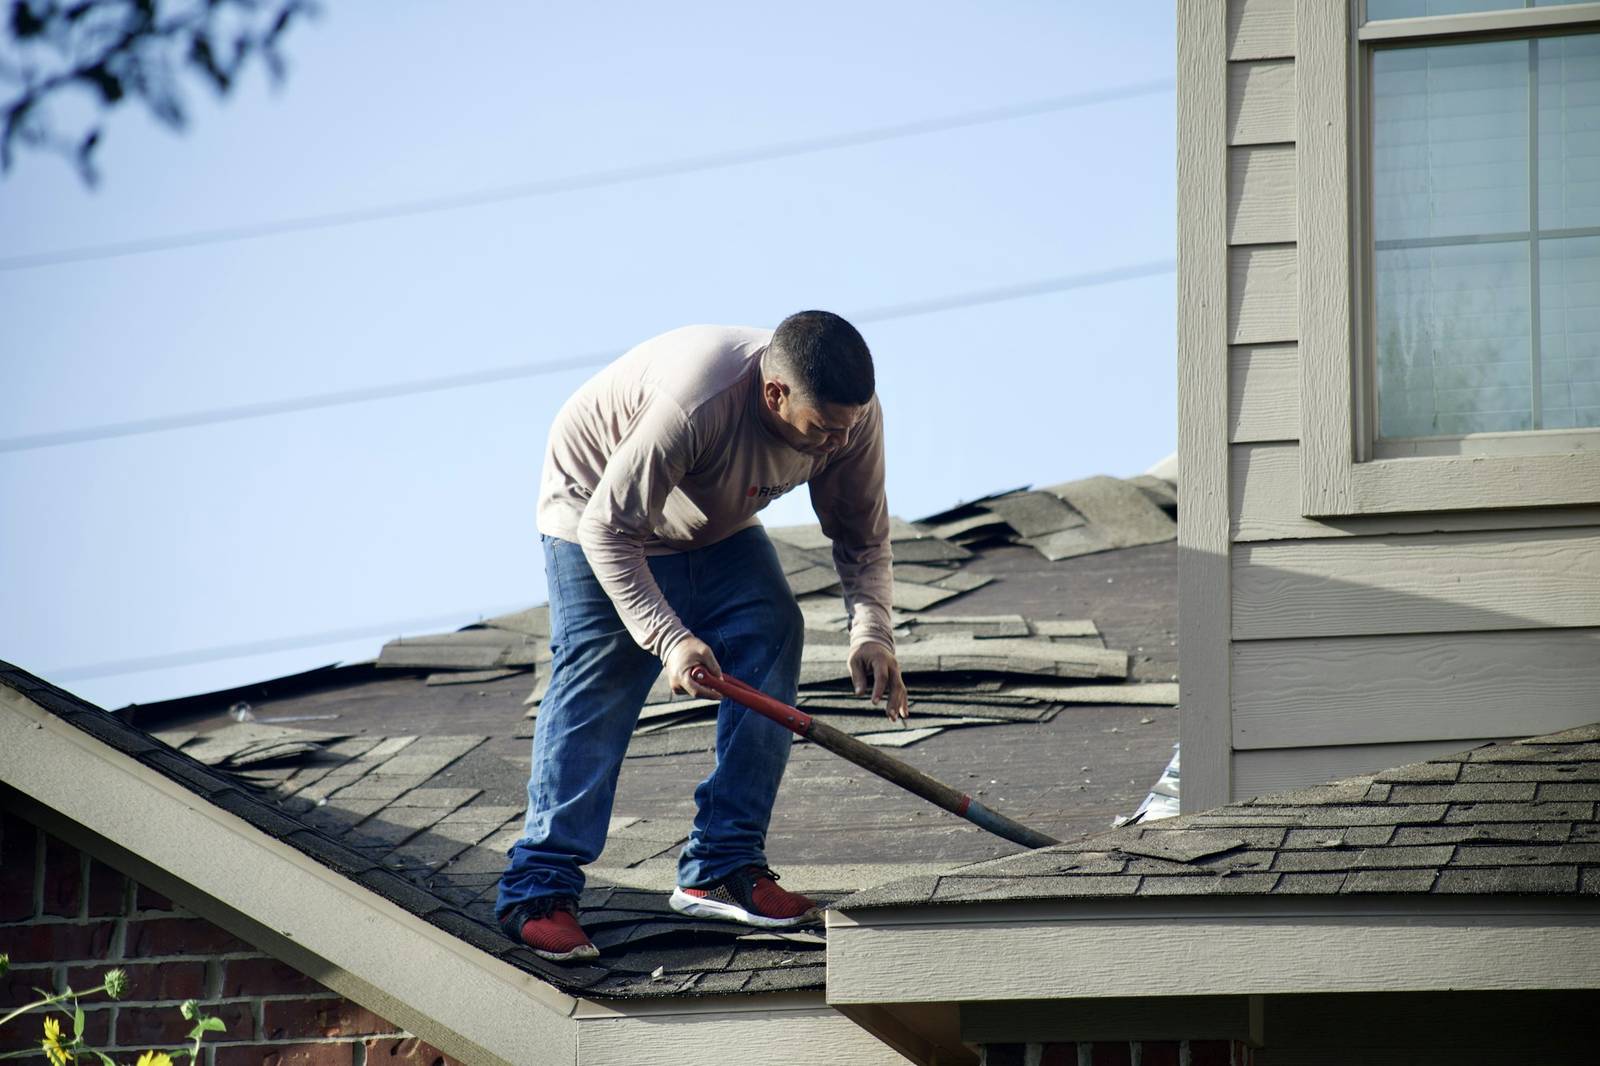
Roofer removing shingles from a house roof
Roof claims

Roof damage claims, done right

Roofs are where we started, and where insurance estimates fall short most often. We inspect the whole roof, document every damaged slope and push for the repair your policy actually pays for.

Common problems

Why roof claims get underpaid

Spot repairs instead of replacement

The carrier pays for a few shingles or a handful of vents when the whole slope is damaged.

Shingles that can't be matched

If your shingles are discontinued, a patch won't match. Shingle identification testing can show whether a repair is even possible.

Missed line items

Starter course, drip edge, ridge cap, underlayment, flashing and vents are left off the estimate.

Hail called "wear and tear"

Hail bruising and wind-creased shingles get written off as age. A proper inspection tells the difference.

Code-required work

Repairs often have to meet current building code, and that cost belongs in the claim.

Depreciation

Older roofs get heavy depreciation. We check how your policy handles it and what you can recover.

Row of houses with brown shingle roofs
What we document

A complete claim, from the start

We inspect the property, write a line-by-line Xactimate estimate and handle the back-and-forth with your insurance company for homes, businesses and churches.

  • Slope-by-slope photos and test squares
  • Hail and wind damage marked and measured
  • Shingle identification for matching
  • Code items and roof accessories
  • Interior leaks and ceiling damage
  • A full Xactimate roof estimate
Questions we hear

Frequently asked questions

My insurance company only paid for vents or a few shingles. Can you help?

Yes. That is one of the most common roof claims we see. We re-inspect the roof, document the full extent of the damage and present the carrier with a complete estimate.

My roof is older. Is it still worth filing?

Often, yes. Age affects how much depreciation is taken, but storm damage is still storm damage. We review your policy to see how roof age is handled.

Do I need a roofer before I call you?

No. You can call us first. If you already have a roofer, we work alongside them so everyone is working from the same scope.

What if my claim was already denied?

Send us the denial letter and the carrier's estimate. We will tell you whether there is a case to reopen the claim.

Roof Claims

Talk to us about your claim

844.975.2100

Or email claims@oceanstates.net with photos and any letters from your insurance company.